Homeowners Insurance in Colorado Springs, CO
Living in Colorado Springs gives families access to some of the most breathtaking views and outdoor experiences in the entire country. However, raising a family at the foot of Pikes Peak also means facing unique weather and environmental challenges that directly impact how we protect our homes.
A Local Guide to Home Insurance in Colorado Springs
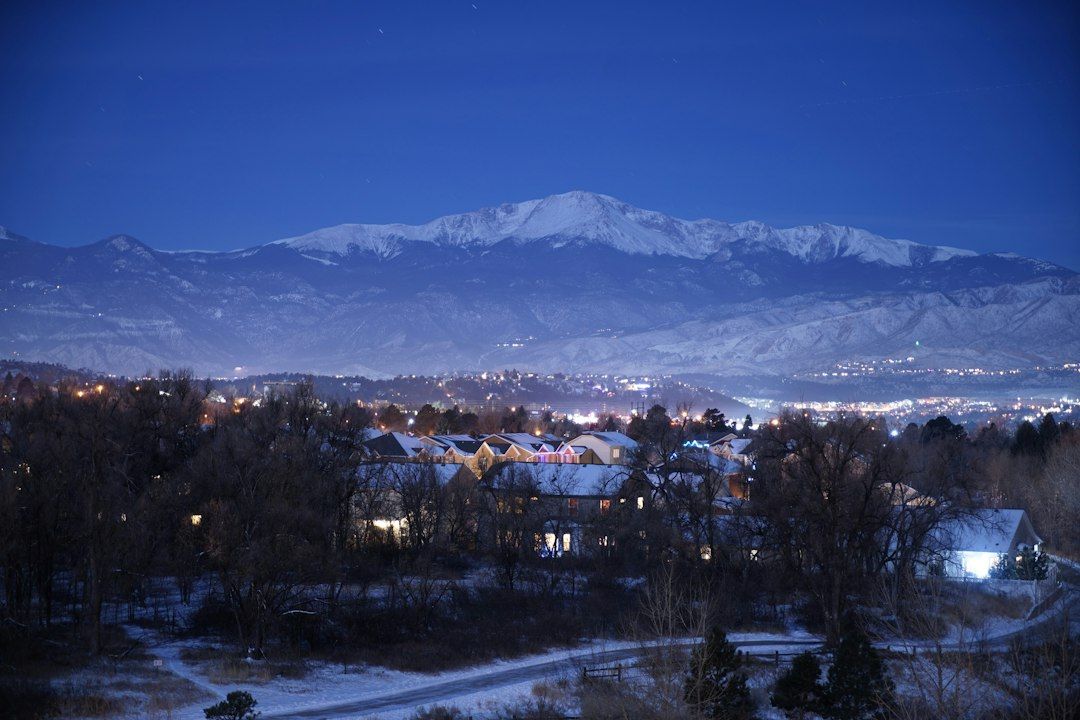
Living in Colorado Springs gives families access to some of the most breathtaking views and outdoor experiences in the entire country. However, raising a family at the foot of Pikes Peak also means facing a unique set of weather and environmental challenges that directly impact how we protect our most valuable asset: our homes.
If you have been shopping for home insurance in Colorado Springs recently, you have likely noticed that the market is changing rapidly. Between extreme weather patterns and evolving insurance regulations throughout 2025 and 2026, finding the right coverage can feel incredibly overwhelming for the average homeowner.
At Kamber Insurance Agency, our mission is to cut through the confusion. We believe that understanding your policy should be straightforward. In fact, we strive to explain complex coverage details so simply that a 12-year-old could understand them. When families know exactly what they are (and are not) covered for, there are no devastating surprises when it comes time to file a claim. This guide is designed to help you navigate the local insurance landscape, understand your specific risks, and make informed choices to protect your family.
Overview of the 2026 Property Insurance Market
Over the last few years, Colorado has climbed the ranks to become the sixth most expensive state for home insurance in the nation. For families looking to secure reliable homeowners insurance in Colorado Springs, CO, premiums have reflected this frustrating statewide trend. Understanding why these costs are rising is the first step toward making smart, informed decisions about your protection.
In our region, we face a double-peril problem. First, there is the ever-present threat of wildfire. While the memories of the Waldo Canyon and Black Forest fires remain fresh for many local residents, more recent catastrophic fires across the state have caused insurance carriers to fundamentally change how they view properties located in the Wildland-Urban Interface (WUI). The WUI refers to transition zones where unoccupied land and human development meet. If your home is nestled in the foothills or surrounded by heavy brush, you are likely in the WUI. Because of the heightened risk, many home insurance companies in Colorado Springs have updated their underwriting guidelines, making standard policies much harder to find for homes in these specific zip codes.
However, the number one driver of rising insurance premiums in our state might actually surprise you. According to reports from the Colorado Division of Insurance, hail damage is the single largest cost driver, accounting for 26 percent to 54 percent of homeowner premiums depending on the county. Colorado Springs sits right in the heart of "hail alley." Because our roofs are constantly in the crosshairs of severe, ice-dropping storms, insurance companies have to account for the high probability that they will need to replace your roof every few years.
To help address these mounting challenges, the state has stepped in with new initiatives. In 2025, Colorado launched the FAIR Plan (Fair Access to Insurance Requirements), which serves as a safety net for property owners who have been turned down by traditional carriers due to high wildfire risk. Furthermore, in the summer of 2026, Governor Jared Polis signed a new law (SB26-155) that created the Strengthen Colorado Homes Enterprise. This program is designed to provide grants to help homeowners fortify their roofs against severe hail, which aims to eventually reduce the volume of claims and stabilize costs for everyone.
Key Aspects of Protecting Your Property
When you sit down to review your house insurance in Colorado Springs, looking at the total annual premium is only a small piece of the puzzle. To truly protect your family, you need to understand the core components of a standard policy and how they apply to the specific risks we face on the Front Range.
Dwelling Coverage and Rebuilding Costs
Your dwelling coverage (often labeled as Coverage A on your declarations page) pays to rebuild the physical structure of your home if it is severely damaged or destroyed. One of the most common misconceptions we see is confusing a home's real estate market value with its replacement cost. The real estate market value includes the value of your land, the quality of your local school district, and current buyer demand. Your replacement cost is strictly the price of the lumber, roofing materials, and labor required to rebuild the exact same house from the ground up today.
Following major local disasters, the cost of labor and building materials naturally skyrockets due to high demand and supply chain bottlenecks. Because of this, it is critical to ask your agent about "Extended Replacement Cost" coverage. This valuable endorsement provides an extra cushion (usually 25 to 50 percent above your stated dwelling limit) to absorb those sudden price spikes so your family is not left paying the difference out of pocket.
Understanding Wind and Hail Deductibles
Because hail is the dominant reason for claims in El Paso County, navigating home owners insurance in Colorado Springs means paying very close attention to your deductibles. Your deductible is the amount of money you agree to pay out of pocket before your insurance company steps in to cover the rest of the bill.
Historically, most people had a flat deductible, such as $1,000 or $2,500, for any type of covered damage. Today, the reality of the local market is quite different. Almost all carriers now apply a separate percentage deductible specifically for wind and hail damage. This is typically set between 1 percent and 2 percent of your dwelling coverage limit. If your home is insured for $500,000 and you have a 2 percent wind and hail deductible, you will be responsible for the first $10,000 of your roof replacement. We always ensure our clients clearly understand this distinction upfront so they can budget accordingly and avoid a stressful financial shock after a major summer storm.
Roof Settlement Types: Actual Cash Value vs. Replacement Cost
Not all roof coverage is created equal. Depending on the age of your roof and the specific carrier you choose, your policy will settle a roof claim in one of two ways.
Replacement Cost Value (RCV) means the insurance company will pay to install a brand-new roof of similar quality, minus your deductible. Actual Cash Value (ACV) means the insurance company will factor in depreciation. If your roof was supposed to last 20 years and a hail storm destroys it in year 15, an ACV policy will only pay you for the five years of life the roof theoretically had left. This can leave you thousands of dollars short. We highly recommend reviewing your home insurance documents to see exactly how your roof is covered right now.
Personal Liability Protection
While weather dominates the headlines, standard policies also provide crucial liability protection. If a guest trips on your icy driveway in January, or if a neighborhood child is injured while playing on your backyard trampoline, your liability coverage helps pay for their medical bills and your legal defense if you are sued. For families with children, pets, or a swimming pool, carrying sufficient liability limits is a non-negotiable part of a secure financial plan.
Insights: Why Protection Always Trumps Price
As an insurance professional with more than 35 years of experience in sales and customer service, I have seen firsthand what happens when people prioritize saving five dollars a month over securing the proper protection. The most heartbreaking situation in our industry is encountering a family that is severely underinsured after a tragedy.
When you evaluate homeowners insurance in Colorado Springs, it is tempting to simply look for the lowest monthly payment. But cut-rate policies achieve those low prices by stripping away the very coverages you will need most during a crisis. After the devastating Marshall Fire in Boulder County a few years ago, data revealed that a staggering 74 percent of affected homeowners were underinsured, with more than a third of them lacking enough coverage to pay for even 75 percent of their rebuilding costs. Families lost everything, only to find out their policies were completely inadequate for current construction rates.
This is exactly why Kamber Insurance Agency operates under the core value of protection over price. Paying a few extra dollars a month for a robust policy can literally save you hundreds of thousands of dollars later. Our goal is to identify any glaring gaps in your current coverage and provide better, more comprehensive options.
Of course, we still look for ways to maximize your savings responsibly. One of the best strategies for managing costs is bundling multiple policies together. For instance, pairing your home policy with your auto insurance in Colorado Springs under the same carrier often triggers significant multi-line discounts. Taking proactive steps to mitigate your risks, such as upgrading to a hail-resistant Class 4 roof or clearing dry brush from around your property, can also open the door to favorable premium credits.
A Simple Checklist for Comparing Your Options
If you are trying to find the best homeowners insurance in Colorado Springs for your family, reviewing policies side-by-side can be confusing. To help you evaluate your current setup or compare new quotes, we recommend using this straightforward checklist:
- Verify Your Dwelling Limit: Does the stated coverage amount accurately reflect today's local construction costs (typically ranging from $200 to $300+ per square foot)?
- Check for Extended Replacement Cost: Does the policy offer a 25 percent or 50 percent buffer if building material costs surge after a widespread local disaster?
- Locate Your Wind/Hail Deductible: Is your deductible for severe storms a flat dollar amount, or is it a percentage of your total dwelling limit?
- Confirm Your Roof Settlement Terms: Is your roof covered for Replacement Cost Value (RCV) or Actual Cash Value (ACV)?
- Review Additional Living Expenses (ALE): Also known as Loss of Use coverage, this pays for a rental home, hotel stays, and food if your house is uninhabitable during repairs. Make sure this limit offers enough funds to support your family for at least 12 to 24 months, as major rebuilds take significant time.
- Assess Your Liability Limits: Do you have at least $300,000 to $500,000 in personal liability coverage? If your assets exceed your underlying policy limits, you should also look into securing a supplemental umbrella policy. If you are unsure how to locate these details in your paperwork, do not worry. You can always check our frequently asked questions or simply ask a trusted local professional to translate the jargon for you.
Conclusion
Finding reliable home insurance in Colorado Springs, CO, requires navigating a complex environment of severe weather, shifting state regulations, and rising building costs. Whether you live in a historic home near downtown or a newer build in the northern suburbs, protecting your property means understanding exactly what your policy promises to do when life takes an unexpected turn.
Ultimately, insurance is about peace of mind. It is about knowing that if a massive hailstorm rolls off the mountains tomorrow, or if a wildfire threatens your neighborhood, your family will not be left to pick up the pieces alone. By taking the time to educate yourself and partnering with an agency that prioritizes transparency, you can confidently secure the coverage your family truly needs.
Let Us Help You Protect Your Colorado Family
If you are a Colorado family with children at home, do not wait until disaster strikes to find out what your policy actually covers. Let Kamber Insurance Agency run a detailed analysis on your current policies to ensure you have zero surprises at claim time. We can review your auto, home, umbrella, or life insurance today so you know exactly how you are protected before the unexpected happens.
Request a quote and contact Seth Kamber now for a clear, no-pressure coverage review focused on truly protecting your family, rather than just lowering your premium. Have an amazing weekend, Colorado, and stay safe out there!
By Seth Kamber & Team · Published 8/11/2026