Home Insurance
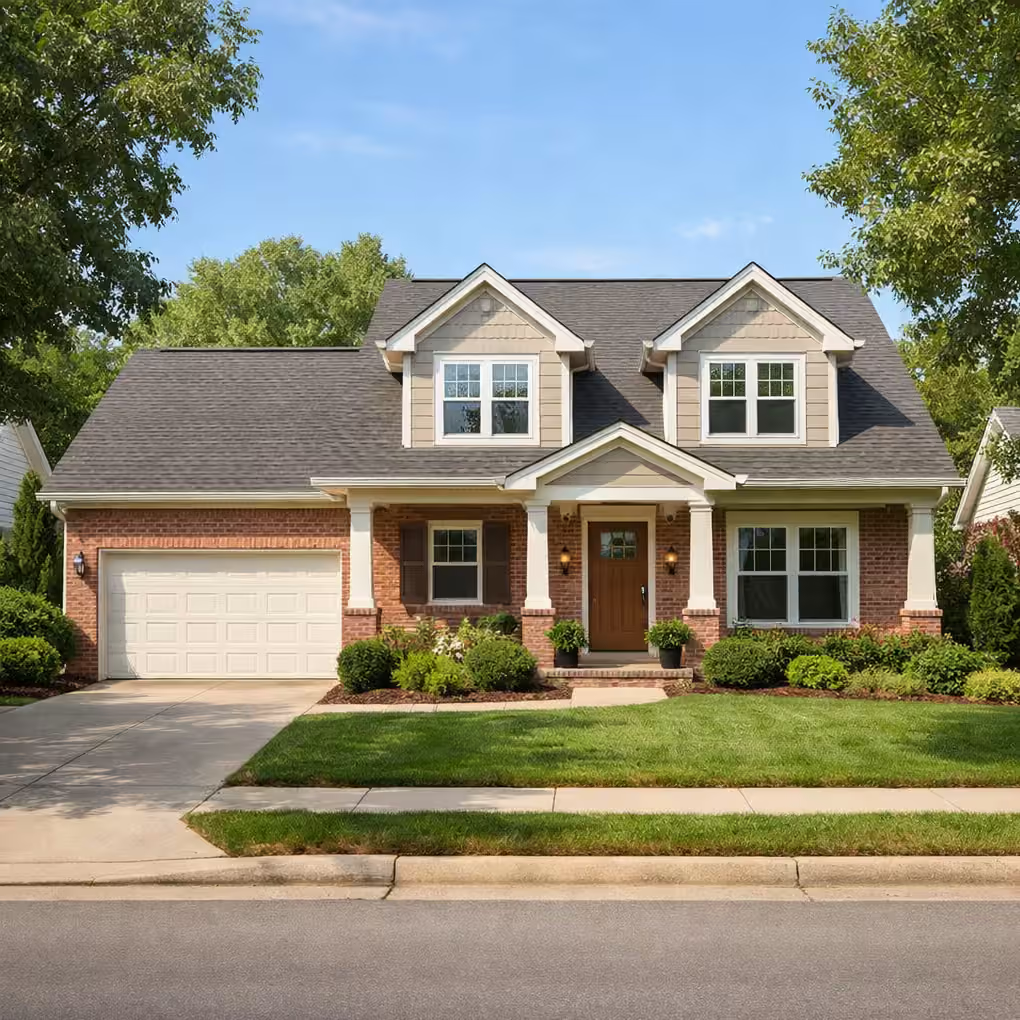
Home insurance can help protect your house, personal belongings, liability exposure, and temporary living costs after a covered loss.
What home insurance can help cover
A strong homeowners policy is designed to protect more than just the structure itself. It can also help with belongings, liability, and temporary living costs after a covered loss.
Review coverage for your home, belongings, liability, and additional living expenses
Compare deductibles, limits, and endorsements based on your property
Get help understanding where standard policies may need extra protection
Protection for your home
Home insurance can help cover repair or rebuilding costs when your house is damaged by a covered loss such as fire, wind, or hail.
Coverage for belongings
Furniture, clothing, electronics, and other personal items may be covered when they are damaged, destroyed, or stolen in a covered event.
Liability support
If someone is injured on your property or you accidentally cause damage to someone else’s property, liability coverage can help with covered expenses.
Extra living expenses
If a covered claim forces you out of your home for a period of time, your policy may help pay for temporary housing and related costs.
How to choose the right home coverage with confidence
Choosing home insurance starts with understanding what you would need to rebuild. Compare dwelling limits, deductibles, and coverage for detached structures so your policy reflects the size, features, and condition of your property. If you've made renovations or added square footage, make sure those updates are reflected in the amount of protection you carry.
Next, review how the policy protects the things inside your home and the risks that come with everyday life. Personal property, liability coverage, and loss-of-use protection can all play an important role if a covered event disrupts your routine or leads to unexpected costs. It's also worth asking whether your belongings are covered at replacement cost or actual cash value, since that difference can affect what you receive after a loss.
Finally, look closely at the situations a standard policy may not fully address. Endorsements for water backup, higher-value belongings, or region-specific weather concerns can help you build coverage with more confidence and fewer surprises later. A quick policy review can reveal gaps before they become expensive problems after a claim.
Common home insurance coverages to review
- Dwelling coverage for the structure of your home
- Other structures coverage for detached garages, sheds, and fences
- Personal property coverage for belongings inside your home
- Personal liability coverage for covered claims and legal costs
- Loss of use coverage if a covered claim makes your home temporarily unlivable
Let’s review your home coverage needs
We’ll help you review your home, belongings, liability exposure, and any optional endorsements so you can choose coverage that fits your property and budget.